
The fenestration sector rarely troubles the front pages of the financial press. Yet the pressures now bearing down on the market are significant. From Washington’s overhaul of aluminium tariffs to Brussels’ tougher approach to building energy performance, the window and door industry enters 2026 facing a combination of regulatory, commercial and supply chain challenges that will test even well-capitalised businesses.
The UK market, estimated to be worth between £3.5bn and £4bn, sits at an awkward point in its development. Regulation is pushing specifications higher, customers remain highly price-sensitive, and the shift from PVC-U towards aluminium and composite products is gathering pace. There is growth, but it is uneven. The question is not simply whether the market expands, but which companies are best placed to capture the value.
The tariff question nobody wanted
The most immediate disruption has come from the US. President Trump’s April 2026 proclamation reshaped Section 232 aluminium tariffs by applying duties to the full customs value of finished aluminium windows and doors, rather than only to the aluminium content within them.
The impact was swift. Tecnoglass, one of the sector’s leading architectural glazing manufacturers, cut its 2026 EBITDA guidance by $50mn within days. For UK businesses, the effect may be indirect, but it is unlikely to be irrelevant. Global pricing, procurement behaviour and material availability are closely linked. Fabricators dependent on imported aluminium systems would be wise to review their purchasing strategies before cost pressures become more difficult to manage.
Regulation becomes a commercial reality
Across Europe, the deadline for transposing the recast Energy Performance of Buildings Directive has arrived. The revised EN 14351-1:2024+A1:2026 standard is now linked to CE marking compliance, and implied window U-values, as low as 0.8 W/m²K in some applications, are beyond the reach of many standard thermally broken aluminium systems without triple glazing.
Specification is no longer a technical detail. It is becoming a commercial filter. Fabricators and systems companies that have invested in certified, high-performance ranges are better positioned to win work. Those that have not may find conversations with architects, developers and contractors increasingly difficult as compliance requirements tighten.
The UK’s Future Homes Standard is adding to the pressure. Implied window U-values are expected to move below 1.2 W/m²K, creating a risk that products meeting today’s Part L minimum requirements could become less attractive in tomorrow’s specification pipeline. For manufacturers, the challenge is not only to meet the next standard, but to make sure their products remain commercially viable once it arrives.
Aluminium continues to gain ground
The shift in materials is well known, but its pace is still easy to underestimate. The number of active aluminium fabricators in the UK rose from 872 in 2019 to 901 in 2025, while PVC-U volumes have come under pressure. Businesses that have diversified into aluminium report the potential to increase their commercial order books by about a fifth.
The trend is particularly clear in bifold and sliding doors, where aluminium continues to dominate design-led residential projects. These categories remain among the stronger-performing parts of the market, supported by demand for larger openings, slimmer sightlines and higher perceived value.
The smart window opportunity
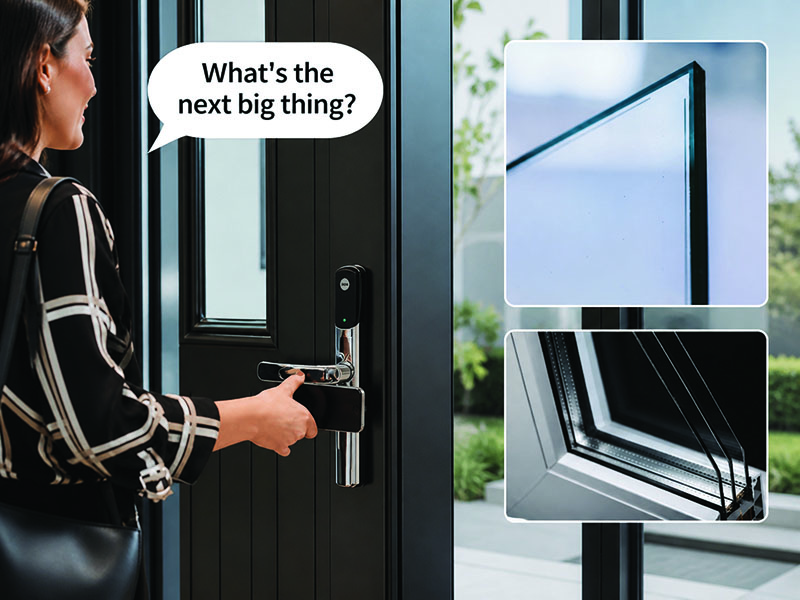
Technology is also starting to matter commercially. The global smart window market, led by electrochromic glazing, is forecast to rise from about $7.2bn today to almost $35bn by 2035. Electrochromic systems have been shown to reduce peak cooling loads by between 25 and 58 per cent compared with standard low-e glass.
In commercial construction, early adopters are already specifying these systems for net zero energy buildings, rather than treating them as a niche premium option. Fabricators and installers that understand the technology now will be better placed to support architects and developers as demand becomes more mainstream.
The fenestration market in 2026 is not short of challenges. But for companies with the right products, the right certifications and a clear understanding of how regulation, materials and technology are reshaping demand, it is also a market with genuine momentum.